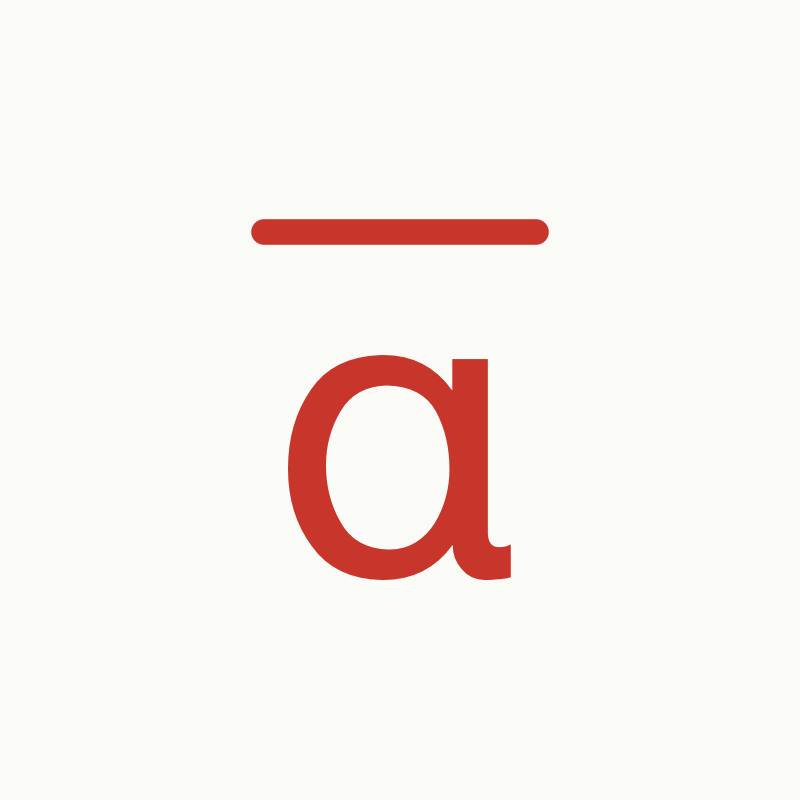
Active Metal Brazed. A ceramic substrate technology used in high-power semiconductor packaging.
GaN
Gallium Nitride. Wide-bandgap semiconductor material used in RF and power applications.
SiC
Silicon Carbide. Wide-bandgap semiconductor material used in high-voltage power electronics.
TAM
Total Addressable Market. The maximum revenue opportunity available if a product served every potential customer segment.
WBG
Wide-Bandgap. Semiconductor material class (SiC and GaN) used in high-efficiency power electronics.
For the full corpus glossary of acronyms used across all essays, see adikumar.co/glossary.
ADI KUMAR · POWER & DIGITAL INFRASTRUCTUREJULY 2026 · V2 · ~50 MIN READ
The AI Power Chain · Part II of IV
Market deep dive · Wide-bandgap semiconductors
The Wide-Bandgap Stack: Boom, Bust, and the Rebuild of AI's Power Semiconductor Chain
SiC and GaN are the enabling materials of the 800VDC data center. Their industry has just come through a capacity glut, reported price declines exceeding 60% across various SiC substrate + epi-wafer categories (specific series vary by source and vintage; not a clean like-for-like index), and the Chapter 11 filing of Wolfspeed, its founding US pure-play. This piece works down the chain from crystal boule to gate driver.
By Adi KumarIndependent analysisViews are my own
Executive summary. Nine findings.
The bust-boom overlap. Wolfspeed emerged from Chapter 11 in September 2025 having cut ~$4.6B of debt (~70%). Over the same period its AI data center revenue doubled in three quarters. The bust was automotive; the boom is data center, and they overlapped.
Prices collapsed. 6-inch SiC epi wafers fell from $600+ (early 2023) to ~$400 by 2025. Chinese 6-inch spot was reported near $200 in mid-2026 on a single trade-press source, not corroborated in Western procurement quotes at time of writing. 8-inch declines exceeded 60% across multiple sources. Chinese substrate capacity went from 460k units (2022) toward a projected 7.7M by 2027.
AI is re-rating the whole chain. Infineon guides AI-related revenue from €1.5B (FY26) to €2.5B (FY27) and sizes the AI power opportunity at ~€12B by 2030. onsemi says content per 1MW AI rack doubled from ~$50k to ~$100k.
Content escalation is the core investable fact. Power component content per rack rises roughly 4x from GB200 to Vera Rubin and ~11.5x to Rubin Ultra. That is a permanent BOM restructuring.
SiC and GaN divide by physics. Voltage and switching frequency split the stack, with SiC in the high-voltage stages up front and GaN in the higher-frequency stages inside the rack. Navitas' 800V-to-6V board that eliminates the 48V intermediate bus is the clearest signal of where GaN is heading.
Substrates have been commoditizing; packaging has held its margin. The scarcity has migrated downstream to AMB silicon-nitride substrates, sinter pastes, and thermal materials, where Japanese and German suppliers together are estimated to hold ~80-90% share of the AMB substrate + sinter-paste + die-attach layer, with Si₃N₄ >95% of the AMB mix. The specific % is a directional estimate from industry-analyst reporting; scope + year of the underlying survey vary.
Gallium is a Chinese export instrument. China's export controls on gallium put GaN's raw-material base under policy risk that SiC's does not carry. The asymmetry between the two technologies is underpriced.
The M&A window is wide open. A post-restructuring Wolfspeed, sub-scale GaN specialists, and distressed Chinese substrate capacity meet buyers (Infineon's "30-30" ambition, onsemi, Renesas, Samsung) who need capacity and design-ins fast.
Bottom-up TAM. WBG devices in AI data centers at roughly $1.5-2.5B in 2026 scaling to $9-14B by 2030 in the base case. The bull case is gated by qualification.
BOULEStage 0 · Wolfspeed
The AI Power Chain · six essays, one physical arc
The series walks a single physical path. It begins at the medium-voltage utility bus at the site fence, steps down through the substation and switchgear, arrives at the datacenter rack where 800V DC is stabilised by the capacitor stack, is converted by silicon-carbide switches to 48V, is distributed across the rack by copper busbars and whips, is stepped down again by multi-phase controllers on the accelerator board to 0.8V, and finally routed through the on-package power delivery network to a transistor gate drawing over 2,000 amperesWaste heat from every conversion stage is removed by the thermal stack. The whole thing is packaged inside a factory-modular building because there aren't enough electricians to build it stick-frame.
Power component content per rack, GB200 to Rubin Ultra
€2.5B
Infineon's FY2027 AI-related revenue target, up from €1.5B in FY2026
The price collapse that defined the cycle
Discrete published price observations, USD per 6-inch wafer, 2023-2026. Note: the series mixes epi-wafer and bare-substrate quotes from different sources. It is a set of observations to be read for direction.
[A1] Woodside Capital Partners (Jun 2025) for 2023 epi-wafer points; eeNews Europe (Nov 2025) for 2024-25 substrate points; DigiTimes via industry press (Jun 2026) for the Chinese spot figure (single-source, unconfirmed). See Annex §A1 for the full reconciliation.
MAPThe framework · Eight layers, one chain
The wide-bandgap value chain, layer by layer
Figure 1 · The WBG arc, 2019-2029
Three phases: EV-thesis capacity build (2019-2023), oversupply and Wolfspeed Chapter 11 (2024-2025), AI-DC demand pull rebuilding the volume chain (2026-2029). Sources: company filings, Yole 2024, NVIDIA GTC July 2025.
Figure 2 · WBG value chain: five stages, each with a distinct vendor structure
Upstream concentration high (wafer / epi); midstream device layer captured by four IDMs on SiC; downstream package + system layers fragmented, where integrator margin is expanding fastest as AI DC volume ramps.
The capacitor stack divides by timescaleThe wide-bandgap chain divides by process stepEach step has a different competitive structure, capital intensity, and margin profile, and the AI transition is redistributing power between them. The map below names the players at every layer. Two things to notice before reading it: the extraordinary Japanese depth in materials and packaging, and how thin the qualified supplier base becomes at the ceramic-substrate and sinter-paste layers. Wafers still hold the attention. The chokepoints have moved above them.
The wide-bandgap power semiconductor market map
Named players by layer, leaders highlighted, and July 2026
The shares quoted are approximate and drawn from public research of differing vintages and scopes. Treat them as positional. Company names are set as text. Several firms appear at multiple layers, which matters: vertical integration is the dominant competitive strategy, and the companies that survived the glut are disproportionately the ones that owned their own substrate supply.
L1Crystal growth & substrates
In brief
Silicon carbide (SiC) and gallium nitride (GaN) are the enabling semiconductors of 800V DC data centres. Five vendors, STMicroelectronics, onsemi, Infineon, Wolfspeed, ROHM, hold over 90% of SiC merchant revenue. Infineon's $830M GaN Systems acquisition (closed October 2023 per company press release) is the largest transaction in the sector. Post-Wolfspeed Ch.11 restructuring, the AI DC positioning question remains open.