
The data centre industry has settled on a comfortable story: AI racks need too much power, and low-voltage AC fails to transmit the current required at scale. The story is true. It is also misleading.
The conversion to high-voltage DC is happening, but treating it as a single phenomenon, driven by power density alone, misses what makes the transition consequential. Three structural forces are driving this shift, and the silicon procurement calendar is pulling the timing forward. Each operates on a different timescale, with different commercial implications. Operators who understand only one of them will design facilities that are technically functional but commercially disadvantaged for the decade ahead.
This essay walks through all three structural forces and the procurement accelerant that pulls them forward. It is the first in a thirteen-part series on the architecture, economics, and competitive dynamics of the DC transition. Subsequent essays will go deeper into specific stages of the value chain, the architectural debates that will drive the next generation of AI data centres, and the operating-model questions, pricing, partnerships, build-versus-buy, that the technical conversation tends to skip.
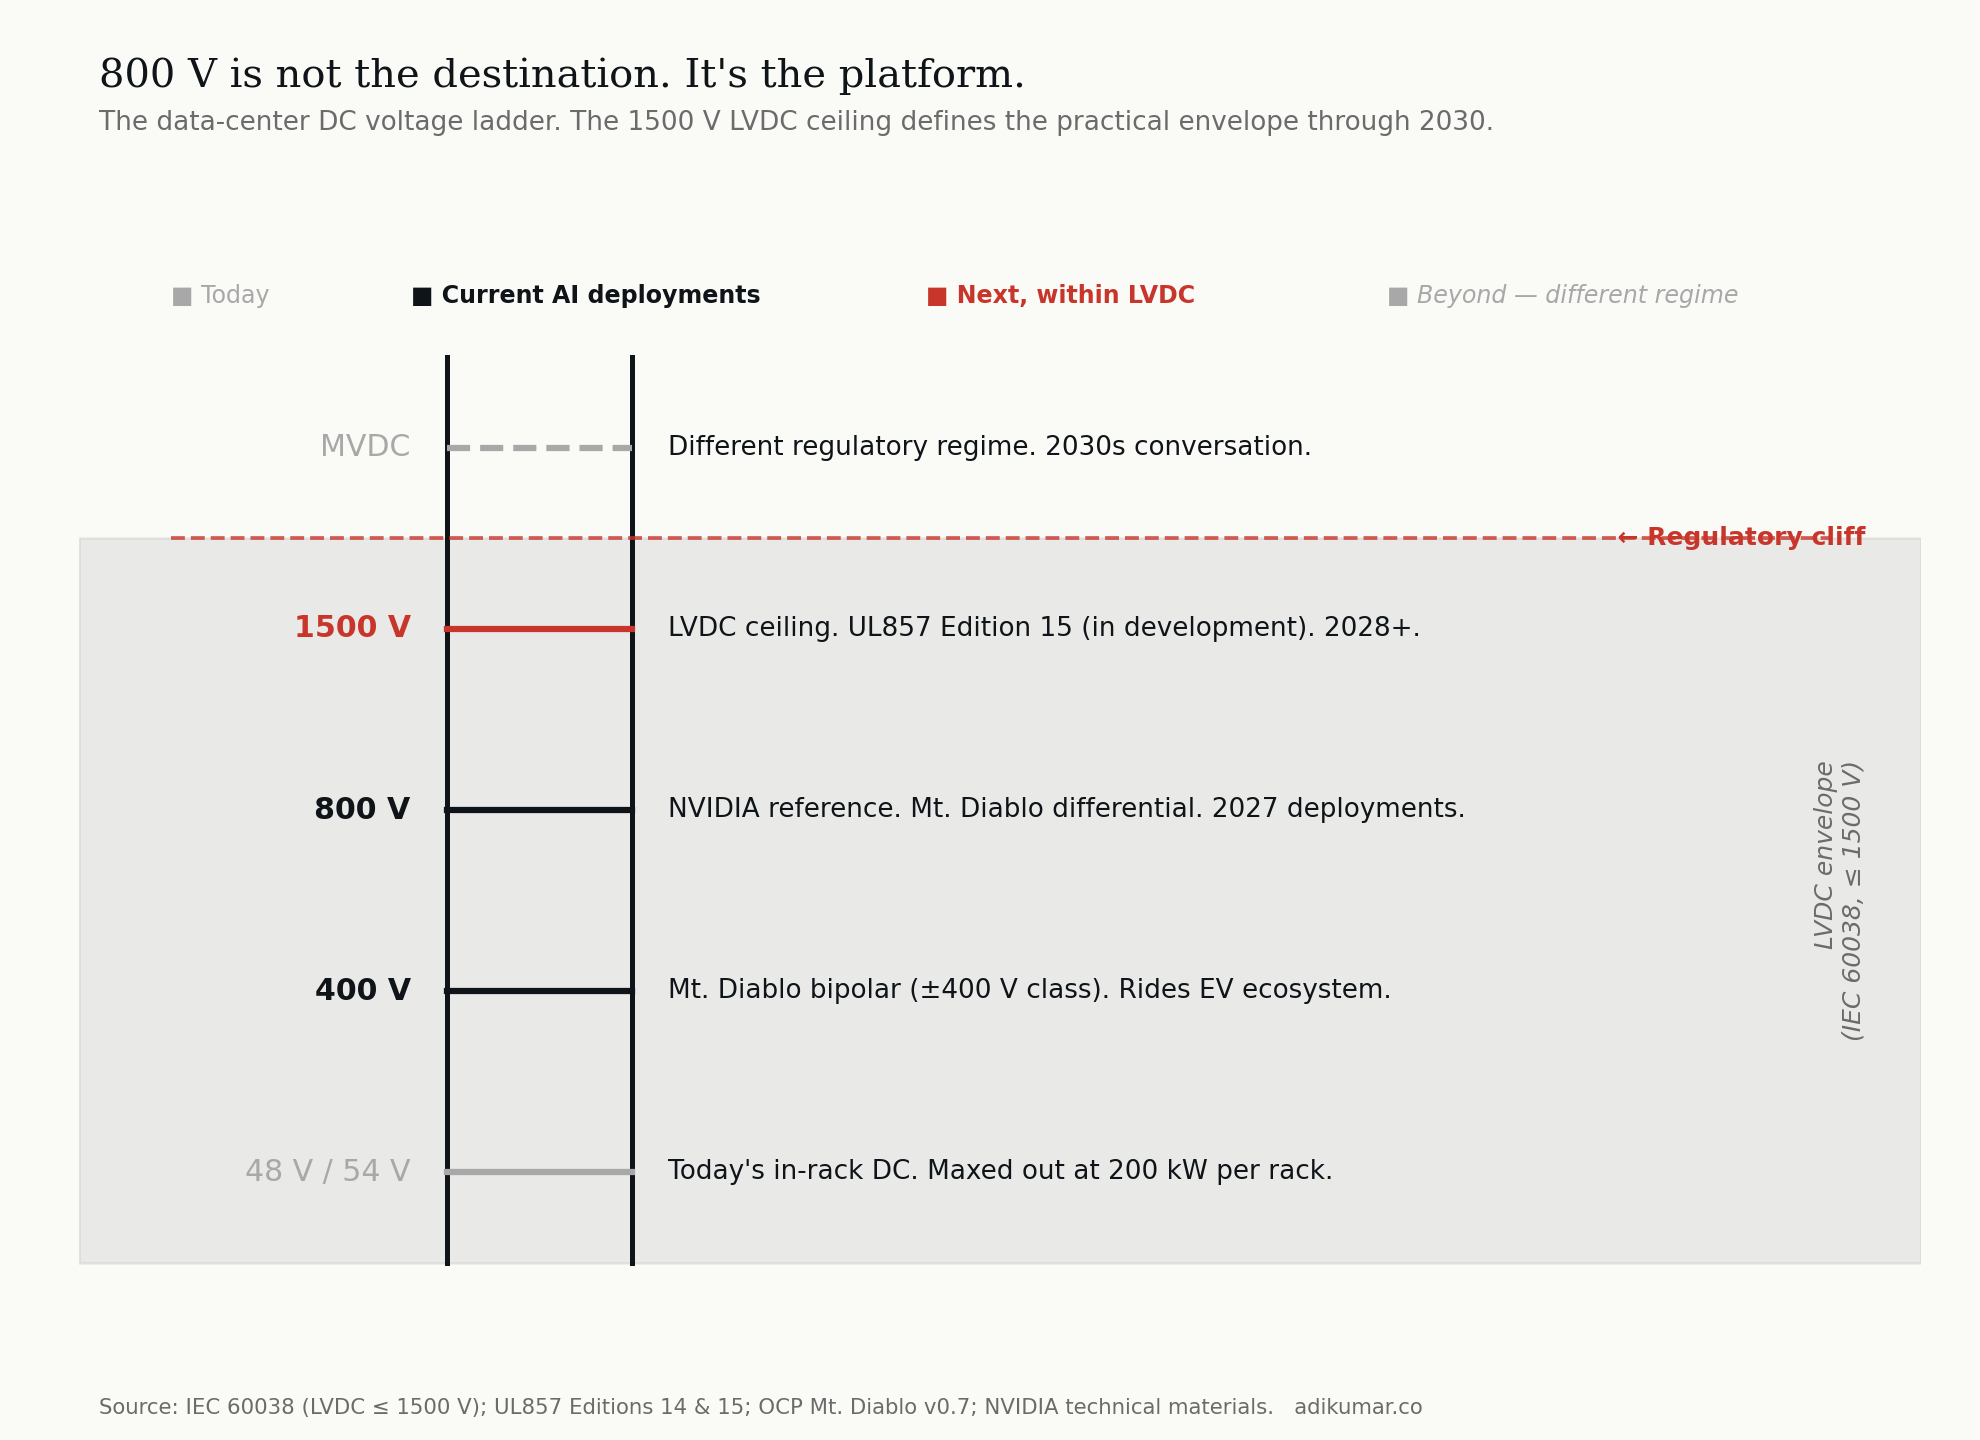
A note on terminology before we start You will see this transition described in trade press as the move to "HVDC" high-voltage DC. IEC frameworks commonly treat systems up to 1,500 V DC as low voltage. That boundary matters for equipment certification, building codes and electrical safety regulation, not just terminology. Anything below 1,500 V on the DC side falls inside the low-voltage DC envelope, or LVDC. The 800 VDC architecture this essay is about , the ±400 V Mt. Diablo specification, and even the 1500 V architectures coming next. All sit firmly inside the LVDC regime. The trade press calls it HVDC because compared to the 12 V and 48 V conventions data centres have used for decades, 800 V feels high. But the standards body has a different view, and so do the regulatory and certification frameworks that govern equipment design. This is more than pedantry. The boundary between LVDC and MVDC at 1500 V is a genuine regulatory cliff that drives which equipment classes operators can deploy through 2030 and beyond. We will return to it in section 7. For the rest of this essay and the rest of the series, I will use 800 VDC and LVDC where they are the technically correct terms. DC transition is the framing for the broader shift across the industry.
1. The physics: copper's inconvenient truth
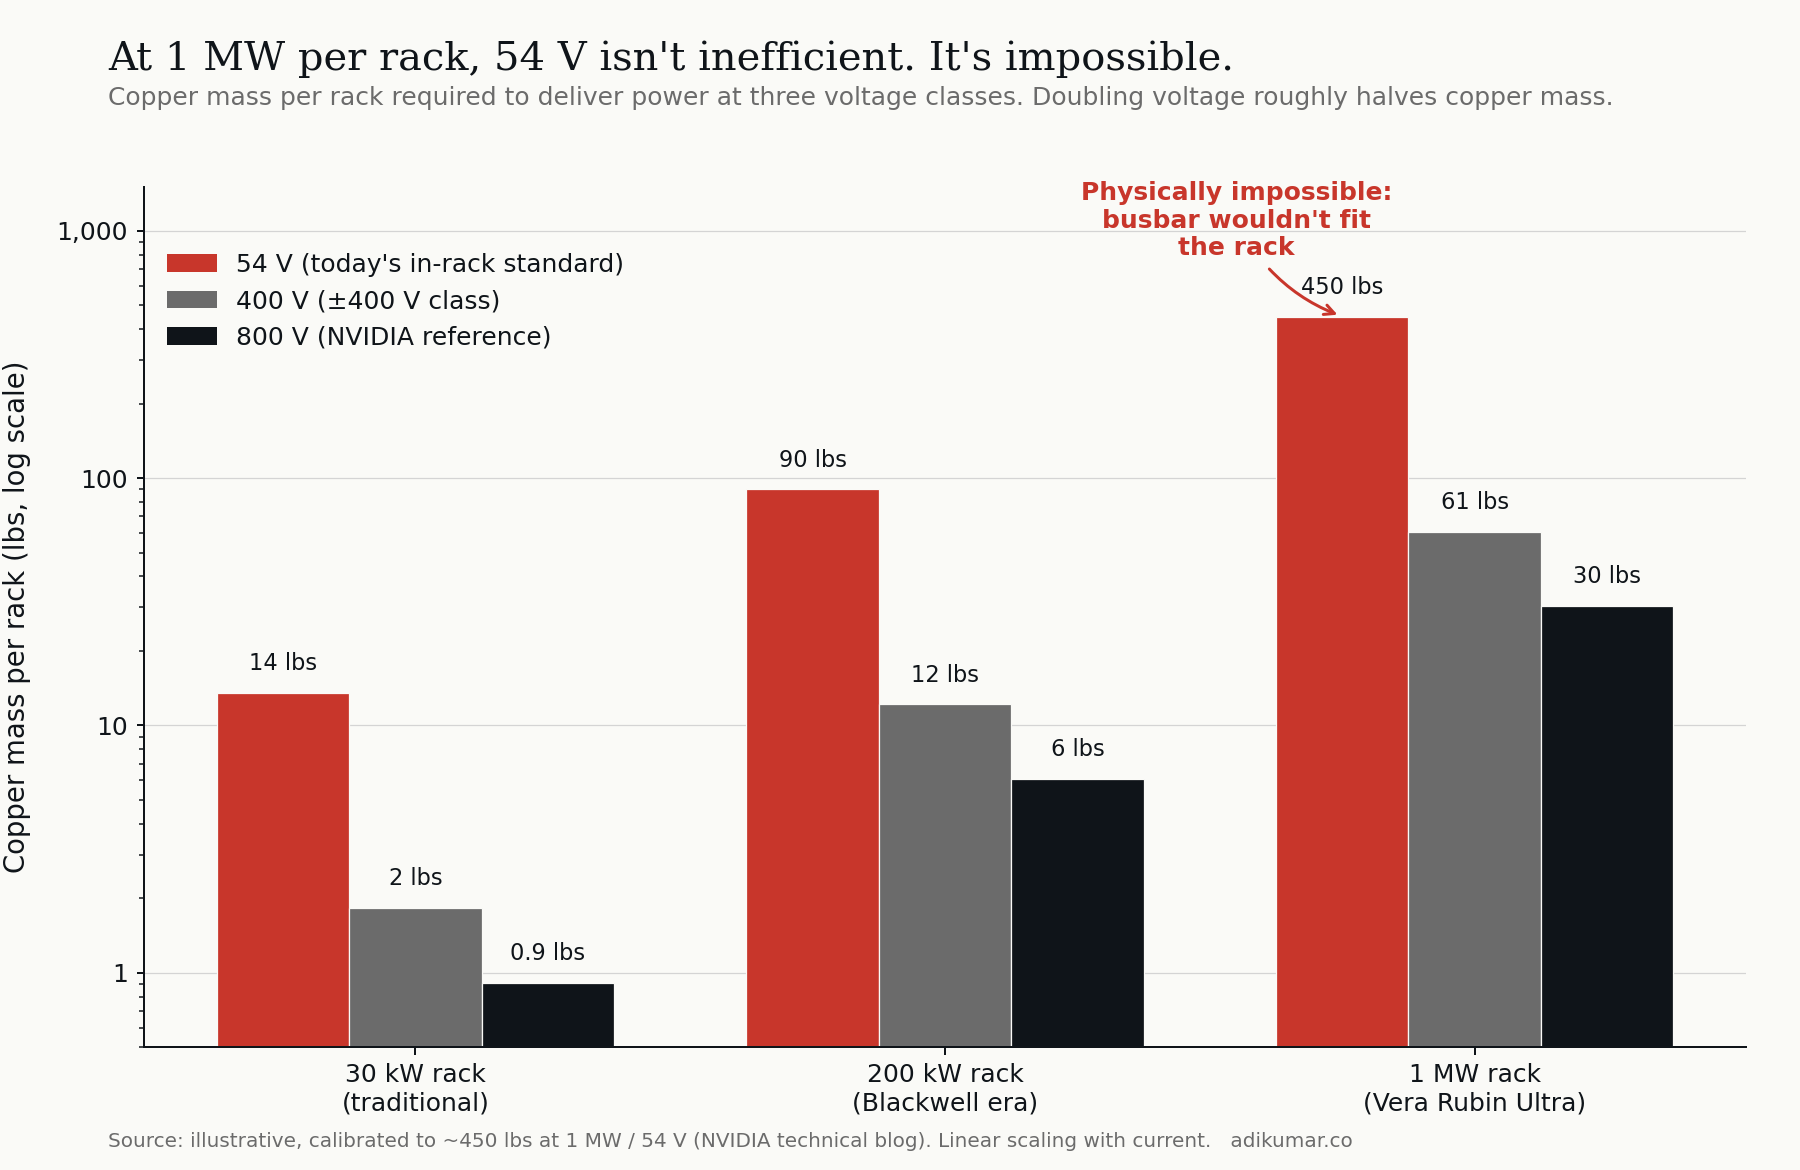
The most straightforward force is the one everyone names. Power equals voltage times current. At fixed power, doubling voltage halves current. Halving current roughly halves the copper required to transmit it without overheating.
For traditional racks at 30 kW, this trade-off is academic. For 200 kW racks (Blackwell-class) it becomes interesting. For 1 MW racks (the Vera Rubin Ultra class) it becomes binary. Nvidia's own analysis puts it at roughly 200 kg of copper busbar per 1 MW rack at 54 V. At that mass, the busbar physically does not fit inside the rack. Not "is inefficient." Not "is expensive." Does not fit.
Voltage doubling roughly halves the copper. At 800 V, the same 1 MW delivers through a busbar that's a fraction of the size and weight, and fits inside the rack form factor.
This is the force every press release names, and it's real. But if it were the whole story, we would simply move from 54 V to whatever voltage transmits 1 MW conveniently, declare victory, and go home. The other three forces explain why we're going much further.
2. The conversion chain: stages compound
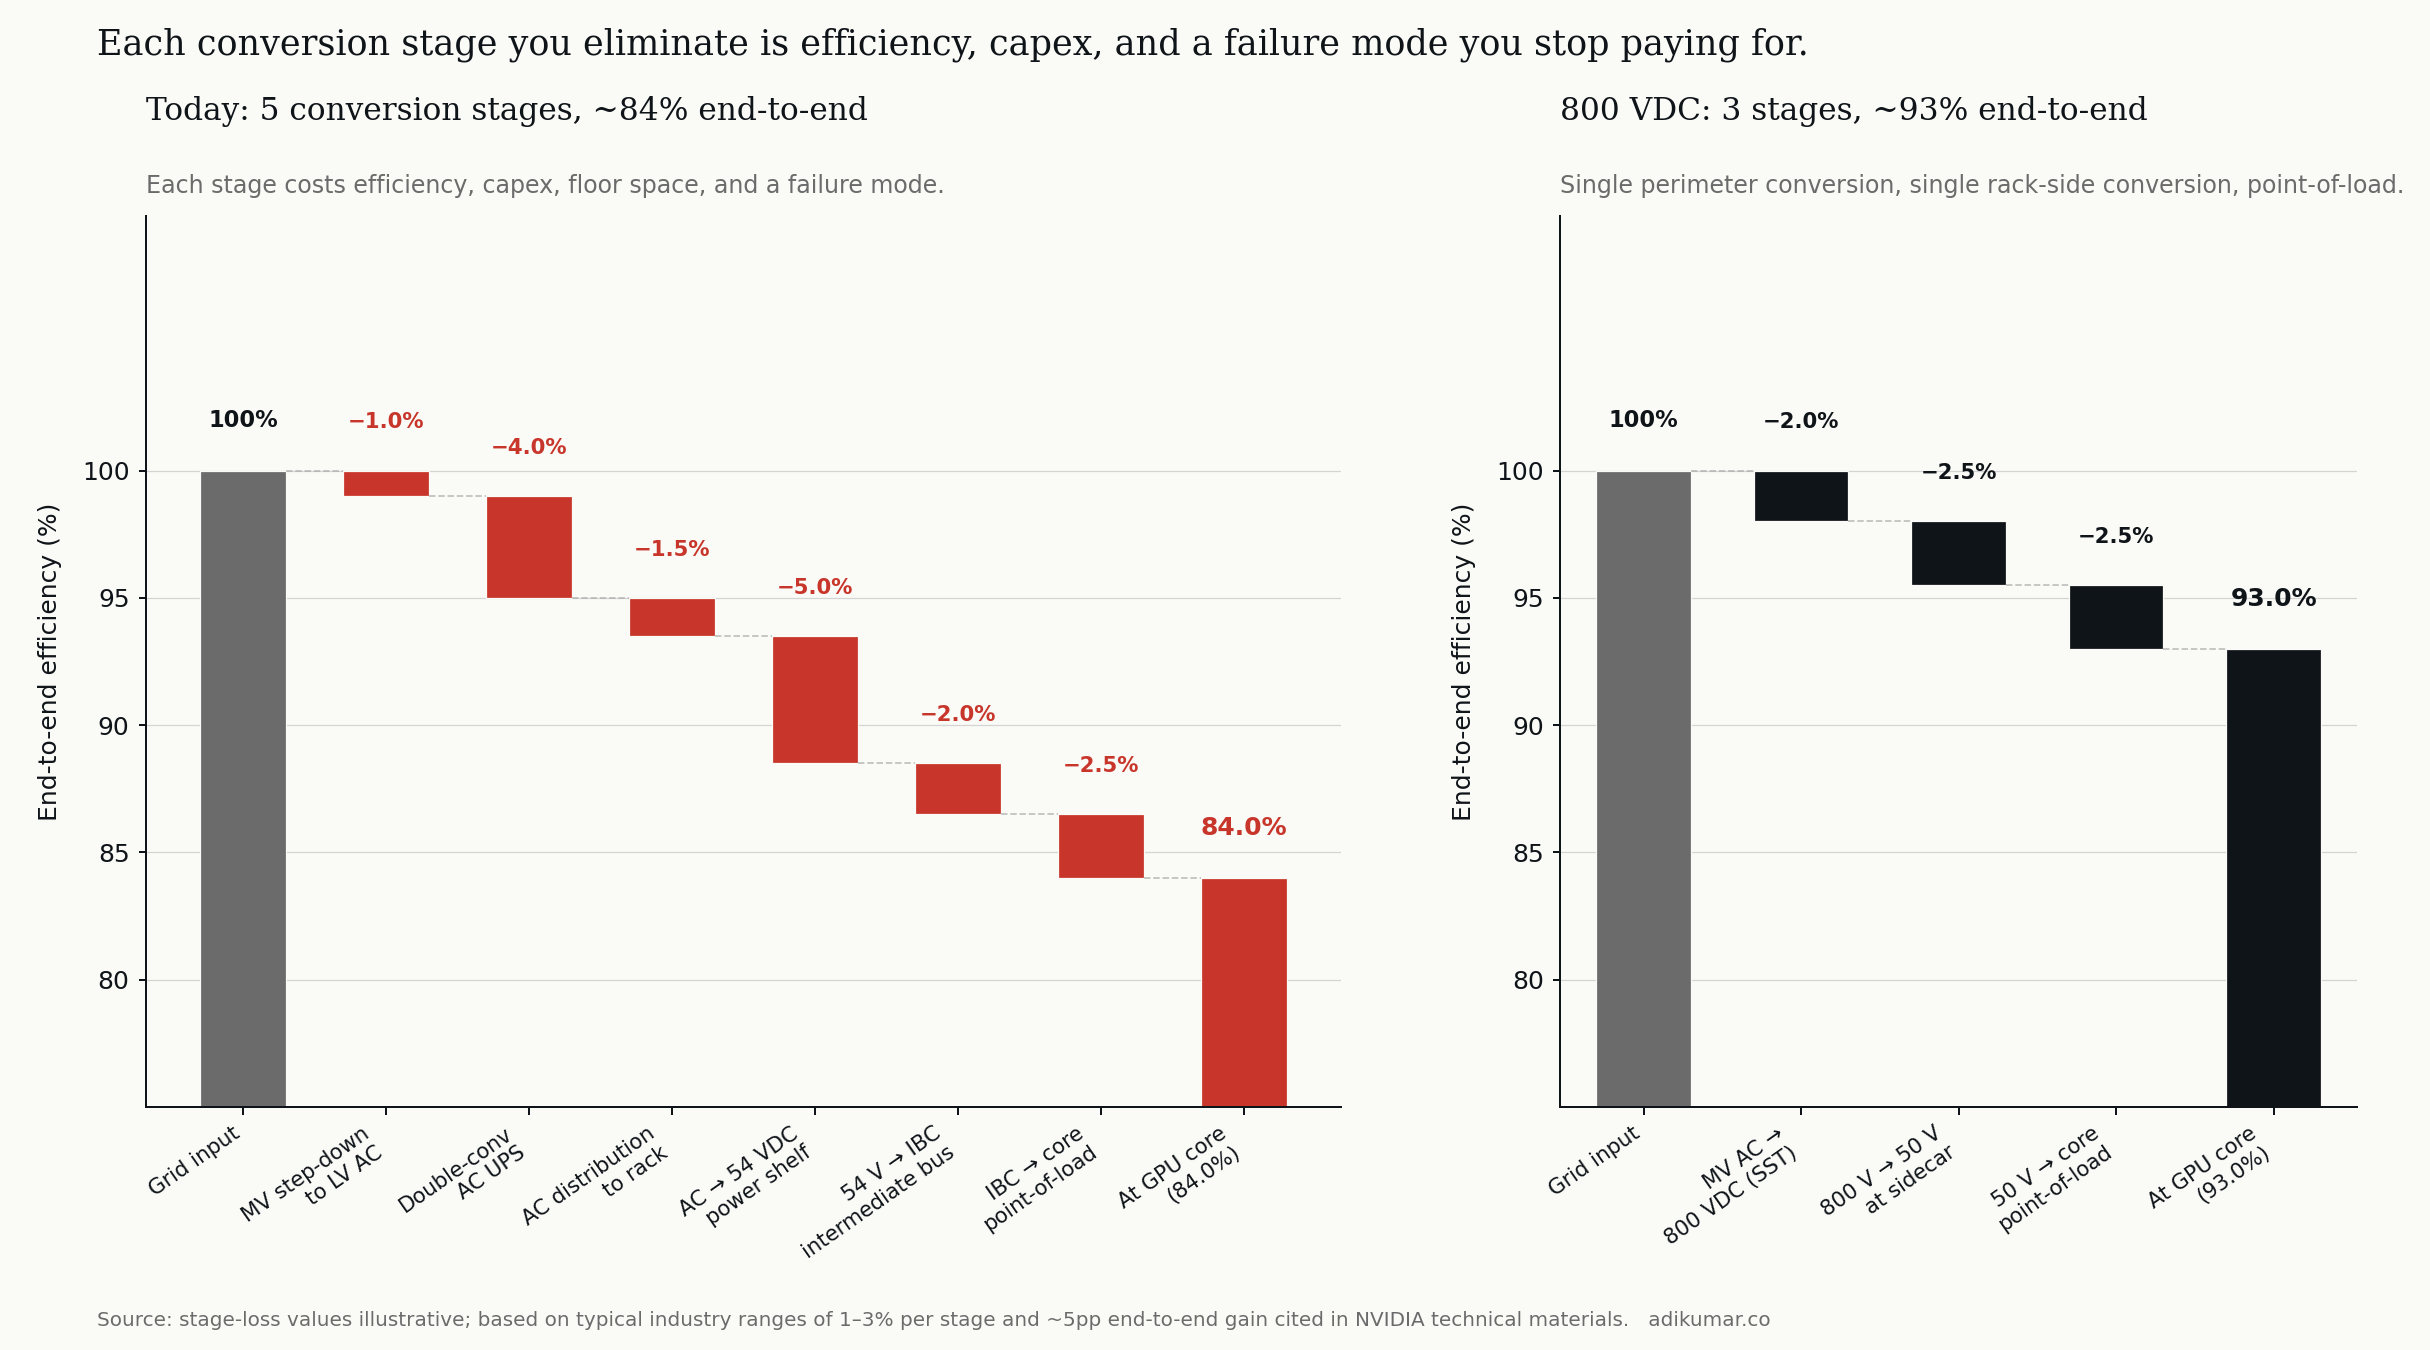
Today's AC architecture for an AI data centre runs through roughly five conversion stages between the grid and the GPU core: medium-voltage AC step-down to low-voltage AC, double-conversion AC UPS for power conditioning and ride-through, AC distribution to the rack, AC-to-DC conversion at the rack-mount power shelf, and a final point-of-load conversion at each accelerator.
Each stage costs efficiency. Best-in-class equipment runs 96-98 percent efficiency per stage; less-than-best equipment runs 93-95 percent. Compound those across five stages and end-to-end efficiency lands somewhere around 84 percent. The exact number depends on where the system boundary is drawn and which topology is being compared; treat 84 percent as an illustrative scenario. For a 100 MW facility on this scenario, the 16 percent loss is 16 MW of waste heat that has to be cooled, plus 16 MW of grid power that has to be procured, paid for, and accounted for in carbon footprint.
The 800 VDC architecture compresses this chain. In the August 2026 OCP standardisation piece from Google, Microsoft and Nvidia, two deployment paths are on the table. A sidecar architecture converts existing 480 VAC to +/-400 or 0-800 VDC in a dedicated power rack adjacent to the compute racks, preserving the upstream AC infrastructure. A direct architecture uses megawatt-scale transformer-rectifier or solid-state transformer skids to convert medium-voltage AC directly to 800 VDC, feeding the whole data hall on a DC backbone. Both paths can reduce conversion stages relative to conventional AC-UPS-to-rack architectures; the direct architecture can reduce them further. End-to-end efficiency moves from around 84 percent under the legacy chain to roughly 93 percent under the compressed chain. The 800 V architecture does not eliminate conversion. It moves the high-current problem upstream and concentrates the remaining conversion closer to the load.
The efficiency story is the visible one. The hidden one is failure modes. Each conversion stage is a piece of equipment that can fail, contains capacitors that age, requires service contracts, has firmware that needs updating, occupies floor space that costs money. Fewer stages mean fewer equipment categories in the operator's reliability spreadsheet. The economic benefit is therefore not confined to conversion efficiency: fewer conversion stages also reduce equipment count, floor-space requirements and the number of active components that have to be maintained.
3. The roadmap: the procurement calendar runs ahead
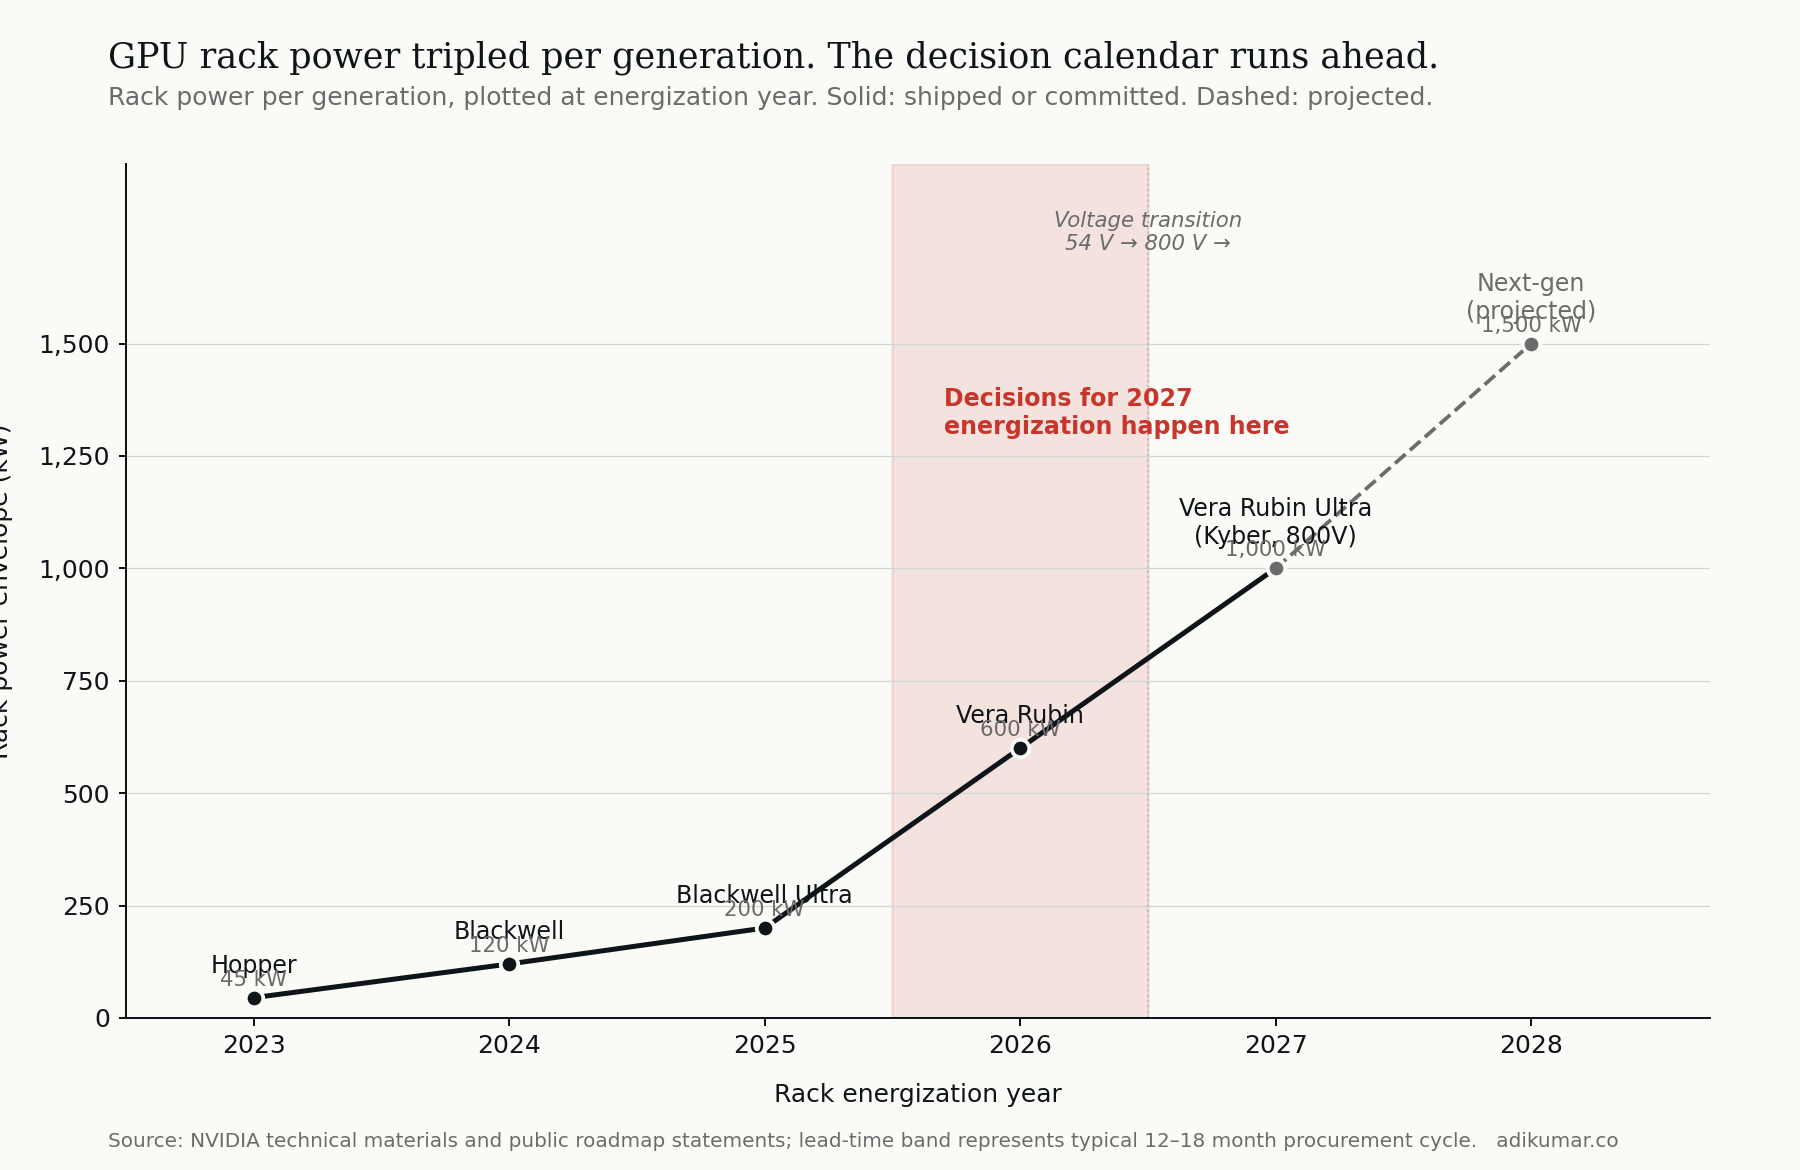
The third mechanism is the accelerant that moves the timetable. Nvidia's rack-power trajectory has climbed sharply generation to generation. The illustrative range, distinguishing documented current designs from stated future targets and industry-projected figures:
- Hopper-class racks: ~45 kW (documented)
- GB200 NVL72 (Blackwell): ~120 kW (Nvidia documented)
- GB300 (Blackwell Ultra): ~200 kW (documented)
- Vera Rubin: ~600 kW (Nvidia stated target)
- Vera Rubin Ultra (Kyber): ~1 MW class (Nvidia stated target)
- Next generation: ~1,500 kW (industry projection)
The trap operators tend to fall into is reading this as a forecast when it operates as a backlog. Each generation's procurement decisions are made roughly 12 to 18 months before energization. A facility coming online in 2027 with Vera Rubin Ultra-class racks has its design locked and procurement committed now, in 2026.
That means the question facing every greenfield AI data centre operator in 2026 moves past "should we build for today's power density?" It is: which voltage architecture do we commit to for the silicon we will deploy in 2027 and replace in 2028? Conservatism, building for 100 kW racks because that is what is installed today, looks cautious on the day of the design decision and commits the operator to two retrofit cycles inside the next four years.
The procurement calendar has eaten the deliberation timeline. Operators who don't see this end up buying decisions they didn't know they were making.
4. The workload: AI training breaks the assumptions
The workload force is the most subtle and the one I find most interesting from an operating-model perspective.
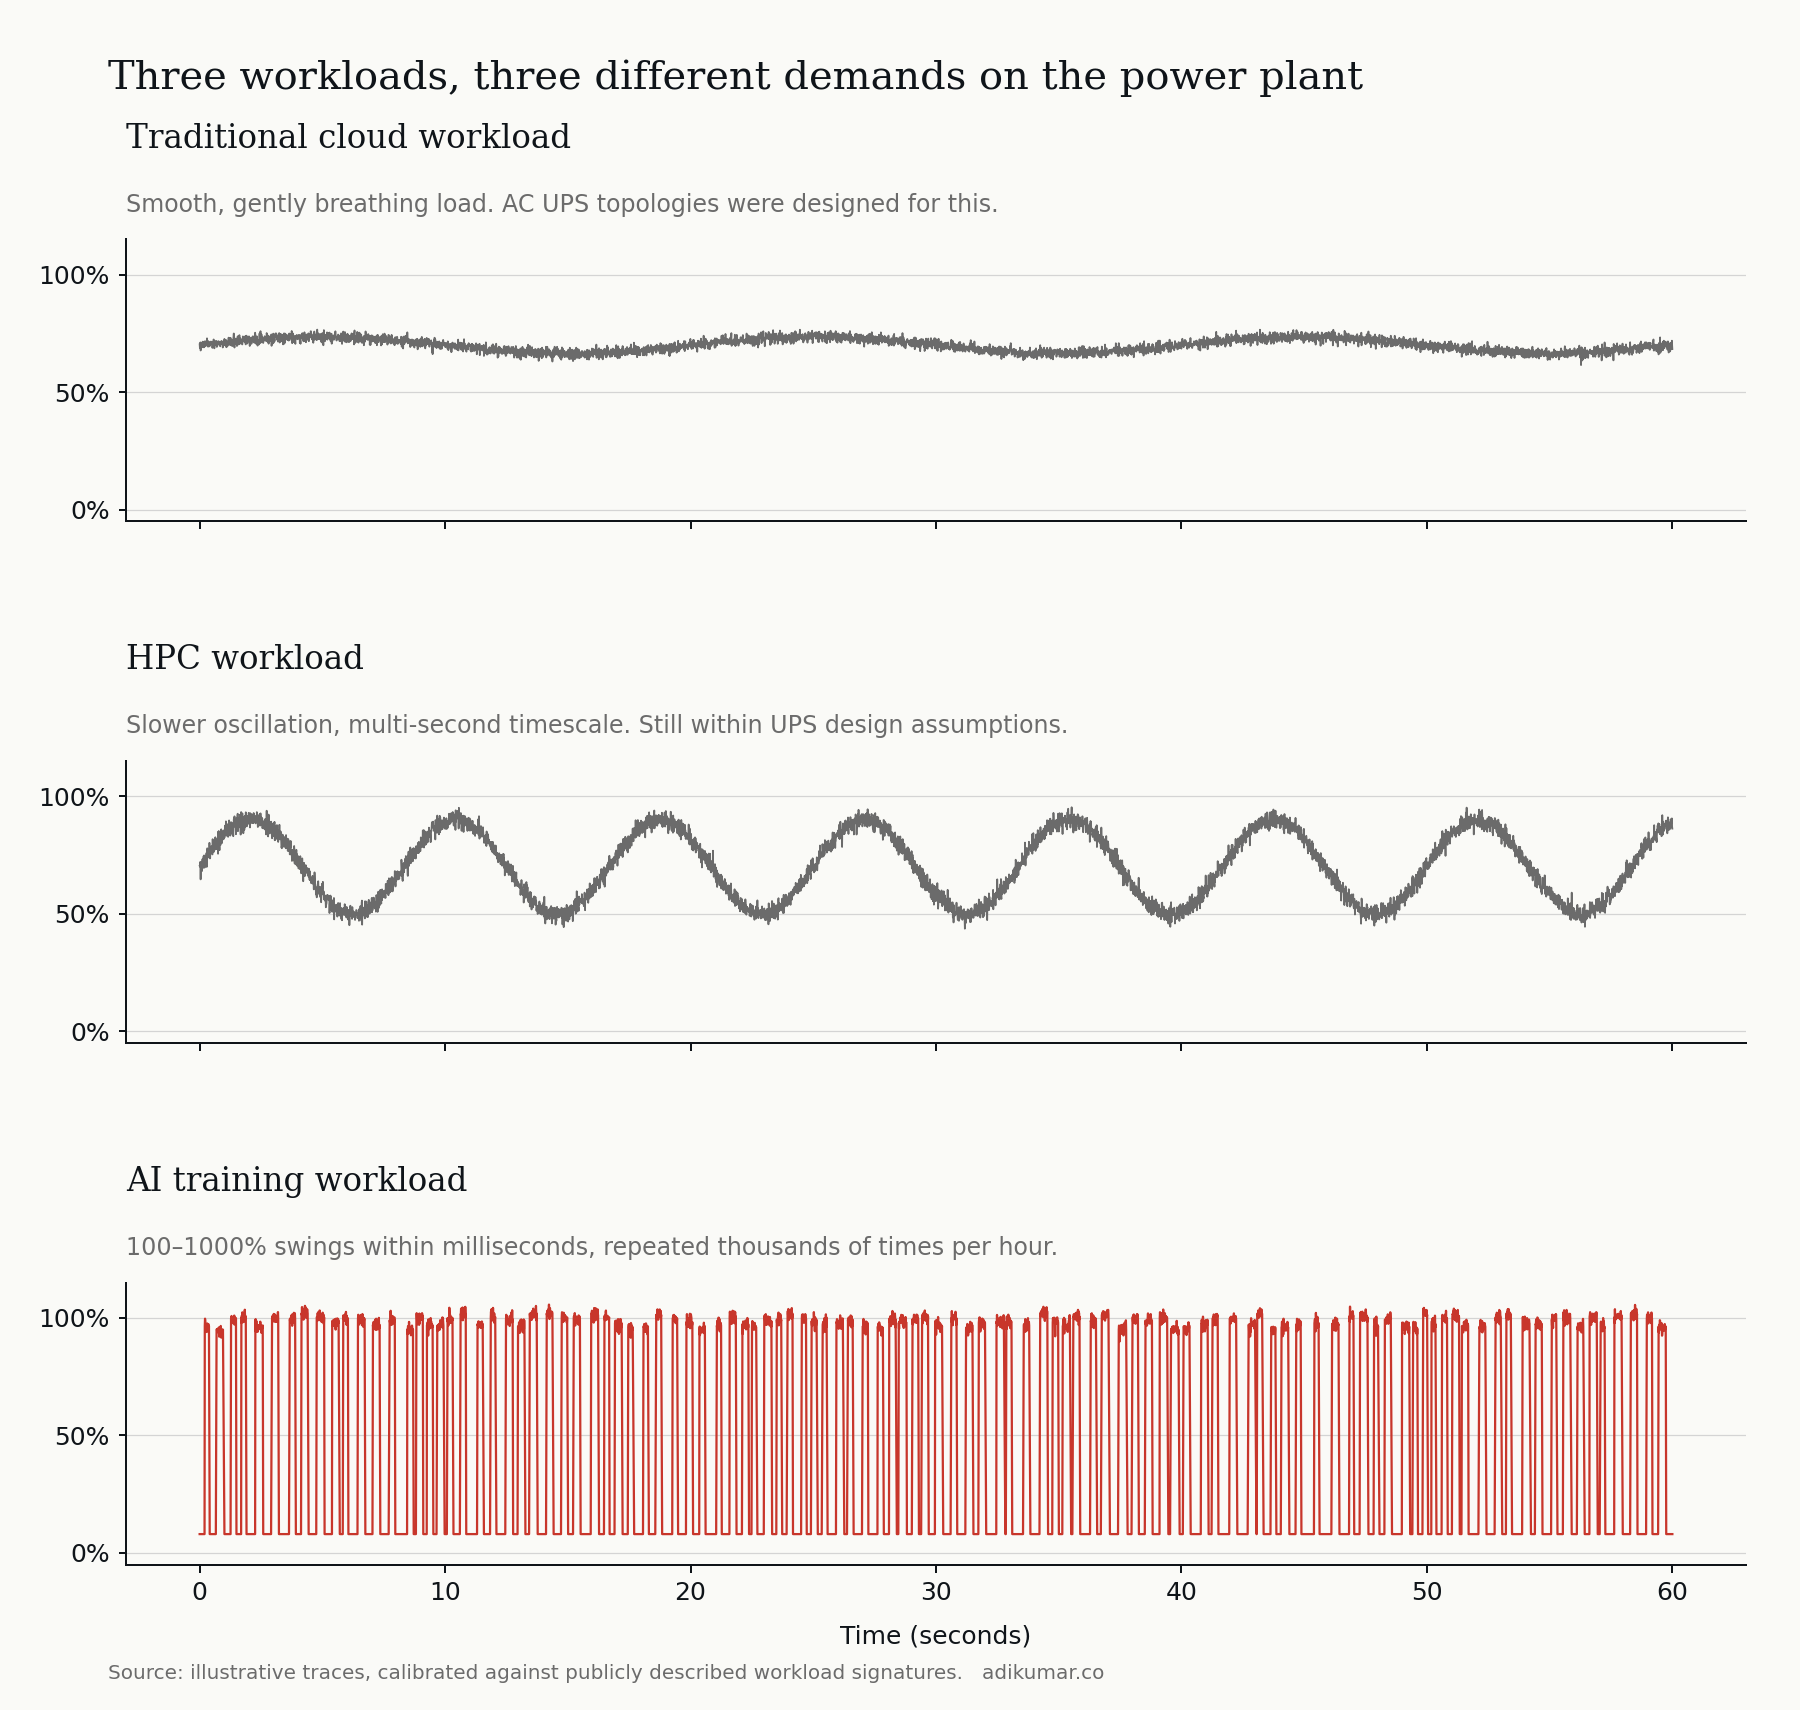
The power-quality assumptions baked into the AC architecture were designed for the relatively steady load, gentle hour-over-hour variation, and predictable diurnal demand patterns of traditional cloud workloads. AC UPS topologies, rotary backup systems, and the control logic that governs them assume the load is well-behaved.
AI training workloads behave non-well-behaved. A large training job synchronizes thousands of GPUs to step in lockstep through forward and backward passes. The aggregate power signature shows step-changes between near-idle and near-peak, repeated thousands of times per hour, with rise and fall times in the tens of milliseconds. From the power-system perspective, an AI training facility can present a highly dynamic load, and at hyperscale those changes can become material at the point of interconnection.
Traditional AC UPS architectures sit outside the design envelope for it. Voltage transients on the grid side, control-loop oscillation, inverter stress, and battery cycling all degrade in the face of high-frequency synchronized swings. Operators are responding with bigger UPS systems, more aggressive grid filtering, and increasingly with on-site battery energy storage (BESS) sized to take on the worst of the swings before they propagate to the utility connection.
DC architectures offer a more direct control point for managing volatility. The intermediate DC bus provides a low-impedance electrical interface between grid-side conversion and the load. Battery storage, the BESS, couples to the DC bus directly, without inverter stages between storage and the demand it is smoothing. The 800 VDC architecture goes past delivering power more efficiently. It puts conversion, storage and power conditioning close to the load in a single control domain.
This is also why utilities are starting to express opinions. A 500 MW AI facility with DC-coupled BESS and active power conditioning can present a different grid interface from an otherwise equivalent AC-coupled design. Interconnection, demand charges, ancillary services revenue depend on the control strategy that the DC coupling enables. The coupling itself is a distribution decision; the control strategy is what changes the utility relationship. The architectural choice affects the utility relationship, and through it, the cost of power for the next twenty years.
5. What do these forces mean together?
Each force, taken alone, is a reason to consider the transition. Taken together, they describe a structural inflection; incremental-upgrade framing understates it.
- Physics sets the floor: around 200 kW per rack, 54 V stops being a comfortable architecture and starts becoming a packaging problem.
- Conversion-chain economics set the medium-term case: each stage you eliminate is efficiency, capex, floor space, and a failure mode you stop paying for.
- Workload behaviour sets the operating envelope: AI's synchronous training loads create rapid power swings that a DC architecture can absorb through DC-coupled storage close to the load.
- The silicon procurement calendar acts as the accelerant. It does not cause the transition. It pulls the decision date forward: if you are designing a 2027 facility, the architectural choice has to be made now.
The mistake I see most often, in conversations with operators, is treating this as an "AI infrastructure" question; the largest power-architecture transition framing captures it better the data centre industry has run since the move from rotary UPS to static UPS in the 1990s. It is the latter.
The standardisation story has moved too. OCP's broader LVDC programme now explicitly encompasses 800 VDC. Google, Microsoft and Nvidia are working through OCP on common requirements for MVAC-to-800 VDC conversion, power quality and system interfaces. Both paths stay in scope: the 480 VAC sidecar for existing facilities, and the longer-term MVAC-to-800 VDC hall architecture. The August 2026 piece names the direct 800 VDC architecture as a common backbone for DC-coupled battery storage (BESS), DC UPS and future DC microgrids. Direct DC coupling simplifies energy storage integration by removing repeated AC/DC conversions and synchronization requirements. The DC bus stops being a distribution layer only. It becomes an active energy-management layer. 800 V is moving from a vendor-specific architecture into an open ecosystem specification. That reframing, from ecosystem standardisation of a distribution voltage to ecosystem standardisation of a control architecture, is the real news of 2026.
6. A note on what this means for everyone who is not training frontier models
The forces above describe what's happening at the leading edge: hyperscalers, AI-specialist neoclouds, the Top 10 AI factory builders. For the rest of the data centre industry, the vast colocation base, enterprise on-prem, mid-market, the question is more nuanced.
A 30-rack colocation hall serving general-purpose enterprise workloads at 10-20 kW per rack does not need 800 VDC. It probably never will. A regional colocation operator with mixed tenant types may need to plan for hybrid facilities where part of the floor is built to legacy specifications and part is built to the new specification. The challenge for these operators moves past the technical decision; it is the commercial decision about which tenants you intend to serve in 2030.
The supplier ecosystem reorganizing around DC Transition will eventually pull mid-market operators forward, but the timeline is much longer. Operators in this segment have time. They should be using it to think hard about which side of the eventual market they want to be on, and to make supplier choices with that in mind.
7. What is the 1500V ceiling, and what comes next?
One question I get often is whether 800 V is the destination or just a waypoint. The honest answer is the latter.
IEC frameworks define the low-voltage DC (LVDC) regime up to 1500 V. Below this threshold, equipment certification, building codes, and electrical safety regulations operate under one set of rules. Above 1500 V, you cross into medium-voltage DC (MVDC), which has different requirements, different equipment classes, and different regulatory regimes.
The practical design space now being explored spans roughly 400 V to 1500 V. Today's reference architectures cluster at 400 V and 800 V because component supply chains support those classes today. The next move, towards 1500 V, is technically straightforward but commercially gated by equipment certification, installation-code development, protection technology and the volume ramp of components rated for the higher class. My base case is 2028 and beyond.
MVDC for data centres is a 2030s conversation, and a different one, with a different regulatory regime, different equipment, and different siting implications. We will get there, but not soon.
8. Three structural forces plus the procurement accelerant
If you remember nothing else from this essay, remember this:
The DC transition in AI data centres is being driven by three structural forces plus a procurement accelerant. Power density is necessary. Conversion-chain economics and AI workload behaviour are each independently sufficient reasons to make the move. The silicon procurement calendar does not cause the transition; it pulls the decision date forward. Together they make the transition not a question of "if" but of "which architecture, on what timeline, with which suppliers."
Operators who understand only the first force will design facilities that are technically functional but commercially disadvantaged. Operators who understand the full set will be the ones positioned to capture the next decade of this market.
9. What's next in this series
This essay is the first of thirteen. The next essay, Two Architectures Wearing The Same Name. Examines the two reference designs that dominate today's conversation: NVIDIA's centralized 800 VDC and OCP Mt. Diablo's bipolar ±400 VDC. They share a name. They share almost nothing else.
Subsequent essays will go deeper into specific stages of the power chain, the safety implications of DC arc behaviour, the supply-chain dynamics, and the operating-model questions that determine which players capture value as this transition compounds.
If you want to follow along, subscribe to the newsletter to get each essay as it publishes.
Reference
Acronyms used in this essay (DC, MV, HVDC, PUE, and others) are defined in the sitewide Adi Kumar corpus glossary.
The DC-DC Transition series now includes six deep-dive supplements addressing specific layer-level questions that the main 13-essay series flagged but did not fully develop. Consulting-grade visuals throughout. Six-layer stack decompositions, vendor concentration matrices, procurement flow diagrams:
- Supplement A. The Transition Tax: domain-by-domain capex decomposition covering where the 800V DC premium accumulates across retrofit and greenfield paths.
- Supplement B. Hybrid Forever: why most facilities will run mixed AC/DC through 2035+. Hyperscaler zone strategies compared.
- Supplement C. The Voltage Ceiling: 1500V DC and the MVDC question. Standards + vendor readiness by voltage class.
- Supplement D. The Solid-State Transformer: Layer 2 supplier dynamics. Western vs Chinese vendor field.
- Supplement E. The Sidecar Power Rack: Layer 4 architecture. OCP Mt. Diablo v0.7.0 reference. 80+ ecosystem partners.
- Supplement F. The Connector Wars: Layer 4/5 interface engineering. High-current connector vendor concentration + failure modes.
Full series index: /tag/dc-transition/All supplements now live.
Capacity is only the visible trigger. Three structural forces are driving the DC transition: rack-power physics, conversion-chain economics and increasingly dynamic AI workloads. The silicon roadmap accelerates the decision because facilities being designed today must support tomorrow's rack densities. 800 VDC turns the distribution voltage into a control point where conversion, storage and power management are co-located.
Frequently asked
Anyone running 800V DC in production at scale (not pilot projects)?
Publicly disclosed deployments remain limited. OCP and hyperscaler work has moved beyond pure feasibility into reference architectures, specifications and ecosystem development. The August 2026 OCP piece from Google, Microsoft and Nvidia formalises 800 VDC as a first-class OCP deployment path alongside the earlier Mt. Diablo sidecar architecture (published March 2026). Specific production-site deployments are generally not publicly disclosed.
How hard is the transition to 800V DC for electricians used to AC systems?
The physical transition is manageable, but the safety, grounding, isolation and DC fault-clearing frameworks differ materially from conventional AC systems and require dedicated procedures and training. OCP's LVDC work identifies DC arc-flash protection as an active industry-development area. The commissioning skillset formalises through the NEC 2029 revision and adjacent installation-code updates.
What is the TCO difference between 800V DC power shelves versus 415V AC UPS?
The TCO depends heavily on topology, system boundary, utilisation, electricity price, resilience architecture and the treatment of UPS/BESS. There is no single defensible percentage applicable to every 100 MW facility. The comparison also depends on whether the reference architecture is a legacy AC-UPS-to-rack topology or a modern hybrid design; see the next section for the illustrative-scenario boundary.
What forces are driving the DC transition beyond capacity?
Three structural forces plus the silicon procurement accelerant. Density economics: 800V DC roughly halves rack copper. Conversion-chain economics: fewer stages, higher end-to-end efficiency, fewer failure modes. Workload behaviour: AI synchronous training swings land better into DC-coupled storage close to the load. The silicon procurement calendar pulls the decision date forward. Capacity growth alone would not have driven the shift.
- SERIES START · you are reading essay 1 of 13
- → NEXT · Essay 2 · Two architectures wearing the same name
- FRAMEWORK MAP · The AI Power Chain framework
- DEEP DIVE · Supplement A · The Transition Tax (capex decomposition)